
The lowest interest rate you see on a bank's website might actually lead to a higher total cost than the package offered right on the showroom floor. It sounds backward, but in the current 2026 market, the "obvious" choice isn't always the one that keeps the most money in your pocket. When you're weighing dealership financing vs bank loan Ohio options, it's easy to feel overwhelmed by the gap between a flashy APR and the final number on your contract. You've likely felt that familiar sting of anxiety about how multiple credit applications might impact your score, or perhaps you're worried about hidden fees tucked away in a bank's fine print.
We understand that you're looking for more than just a car; you're looking for a fair deal from someone who treats you like a neighbor. Whether you're eyeing a rugged new RAM truck for the job site or a refined Jeep for weekend trips, this guide promises to simplify the financial jargon into clear, actionable steps. We'll compare the latest 2026 lending data, explore how local Ohio credit unions stack up against dealer incentives, and show you how to minimize your time spent in the finance office while securing a payment that fits your life perfectly.
Key Takeaways
- Understand how 2026 Ohio lending trends and current credit score expectations directly impact your ability to secure a low monthly payment.
- Learn why obtaining a bank pre-approval serves as a vital baseline before you compare dealership financing vs bank loan Ohio options.
- Discover the unique advantages of dealer-arranged financing, including exclusive access to manufacturer-backed rates and promotional incentives from Chrysler Capital.
- Find out how to use professional trade-in tools like the KBB Instant Cash Offer to lower your total loan amount and simplify the paperwork.
- Master a simple, step-by-step strategy to minimize your time in the finance office while ensuring you land a deal that fits your budget and lifestyle.
Understanding the Ohio Auto Finance Landscape
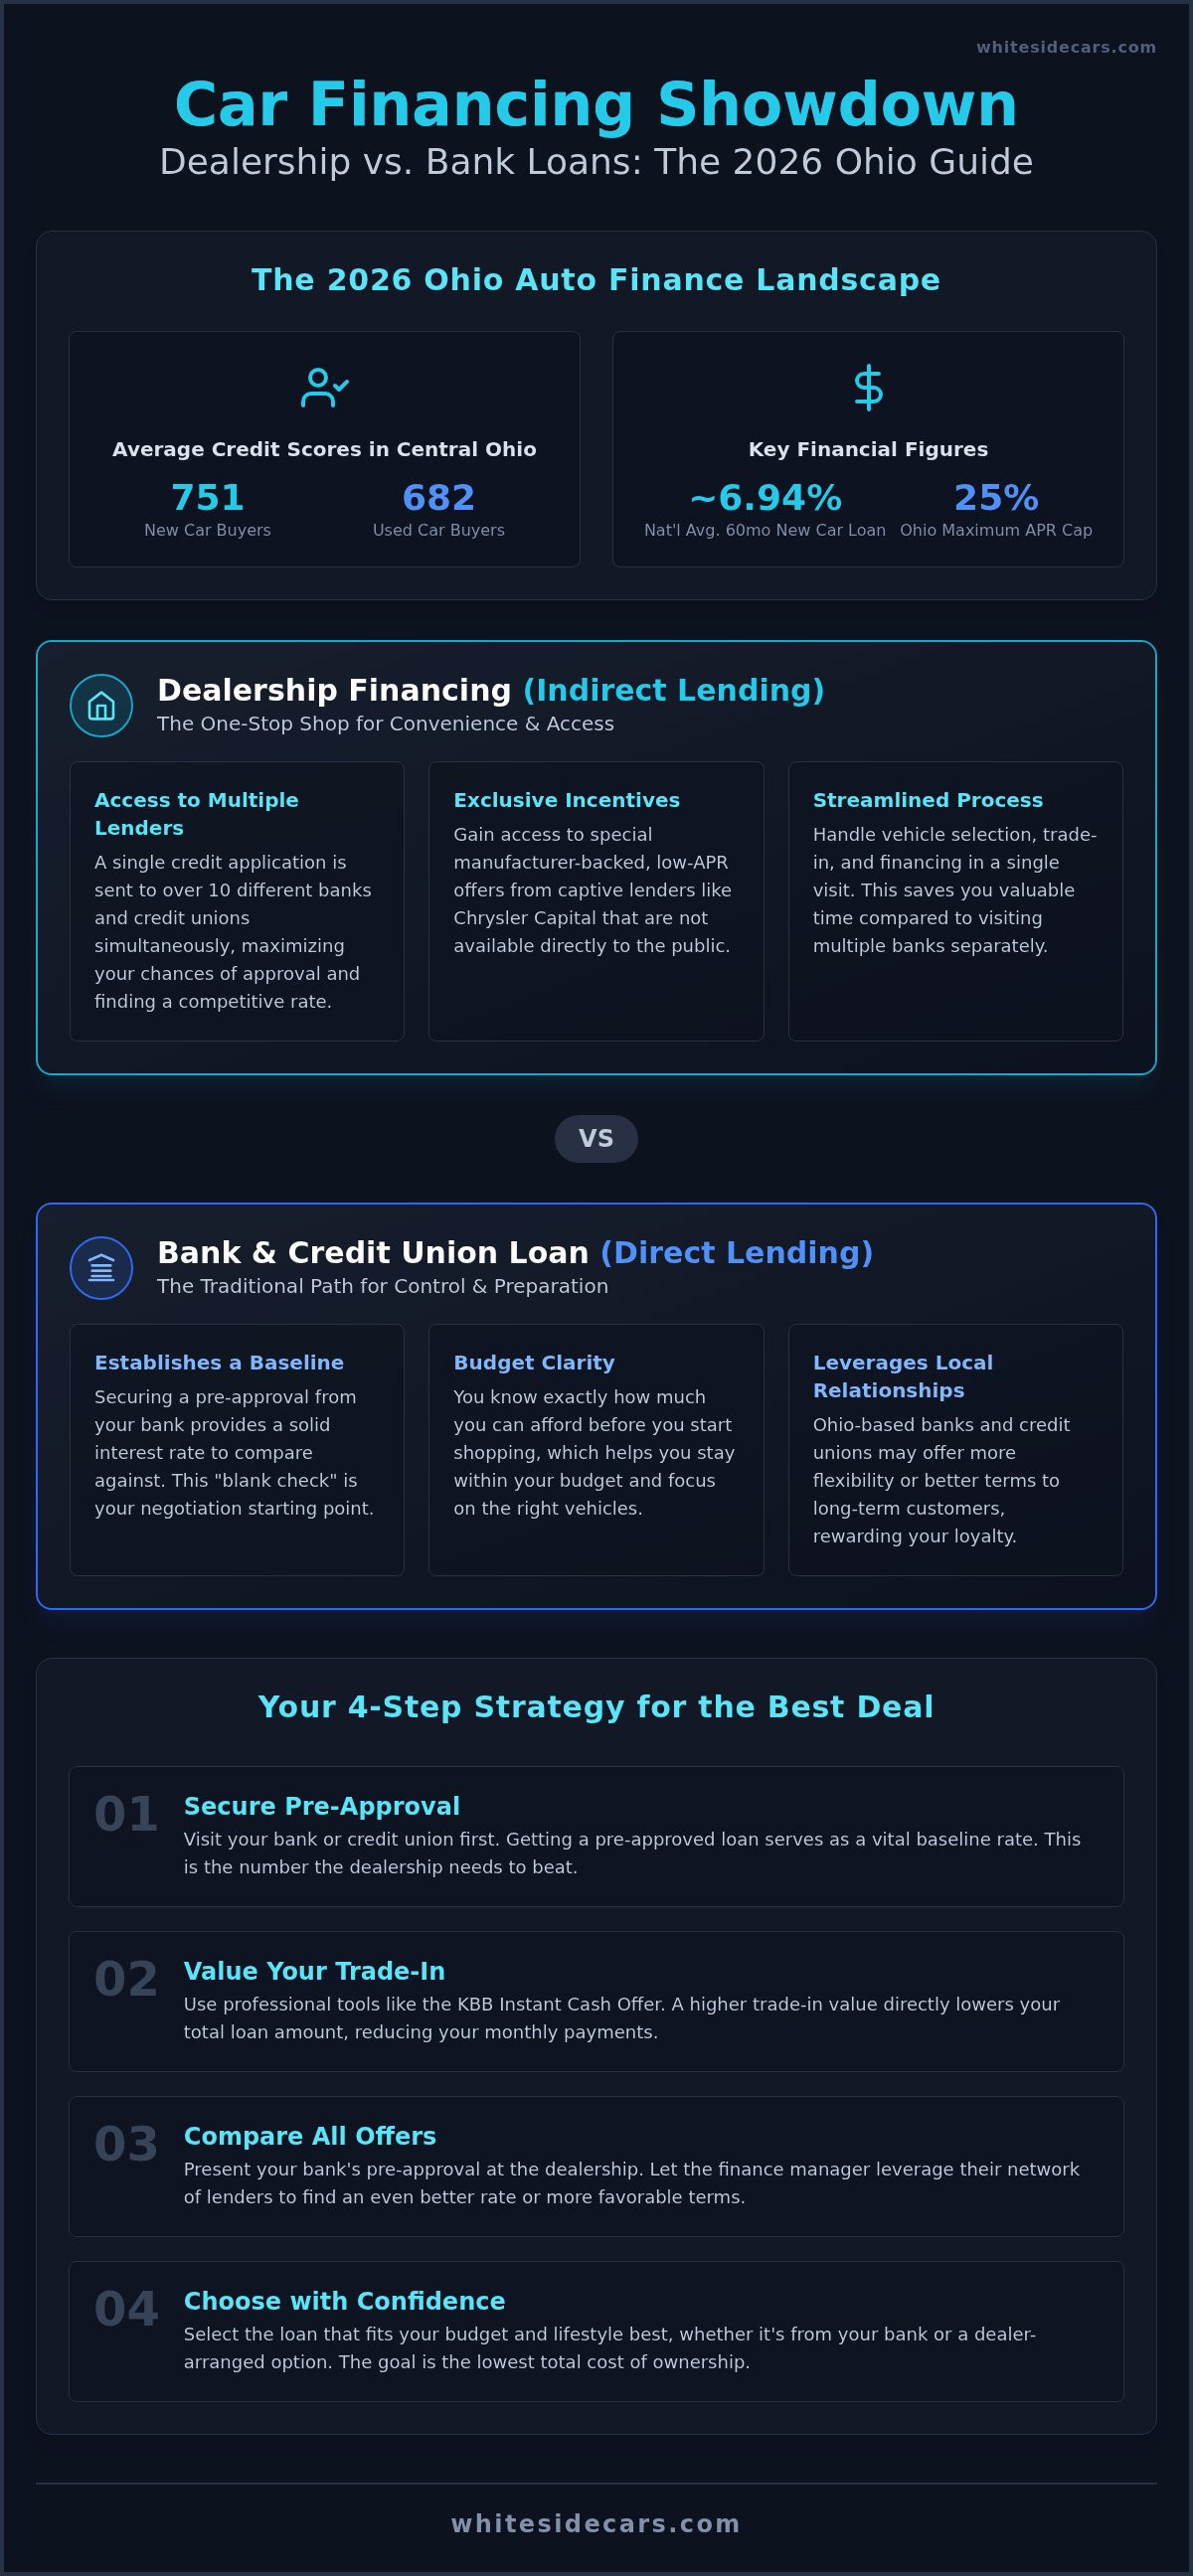
The finance landscape for Ohio drivers in 2026 is a blend of high-tech tools and hometown trust. Whether you're commuting from Grove City or running errands in Mount Sterling, your credit score remains the primary factor in your lending journey. Recent data from Experian shows that new car buyers in the Columbus region carry an average credit score of 751, while those looking for a used vehicle average around 682. These numbers aren't just digits; they're the keys that unlock specific interest rates and terms across our local market. Understanding where you stand helps you set a realistic budget before you even sit in a driver's seat.
In our corner of Ohio, drivers often find themselves juggling multiple options from local branches. With the national average interest rate for a 60-month new car loan sitting at approximately 6.94% as of August 2026, the competition among lenders in Madison County is fierce. This environment is actually a win for you. When banks and credit unions compete, they often sharpen their pencils to offer more attractive terms to keep your business close to home.
Direct vs. Indirect Lending Explained
When you start exploring Car Finance Options, you'll encounter two main paths: direct and indirect lending. Direct lending is the traditional route where you visit a bank or credit union in person to secure a loan commitment. You handle the paperwork yourself and bring a "blank check" to the dealership. It's a solid way to know exactly what you can afford before you start shopping for a new RAM or Jeep vehicle.
Indirect lending, however, happens right here at the Tom Whiteside CDJR finance office. We act as the representative, sending your application to a variety of local and national lenders simultaneously. Indirect lending serves as a helpful bridge between local buyers and a massive network of national credit providers. This process often saves you a trip to the bank and allows our experts to compare several offers at once to find the best fit for your specific credit profile.
The Local Ohio Advantage
Regional banks in Grove City, London, and Mount Sterling often have unique lending criteria that differ from the big national institutions. They understand the local economy and may offer more flexibility for their long-term neighbors. When you're weighing the dealership financing vs bank loan Ohio debate, remember that local market competition directly benefits your bottom line. Ohio state regulations also play a major role in keeping things fair. For instance, the maximum APR for dealer-arranged retail installment contracts is capped at 25% in Ohio, providing a clear ceiling for consumer protection.
Transparency is a hallmark of the Ohio car market. The Ohio Consumer Sales Practices Act protects you from deceptive conduct, and as of April 2026, the state increased the surety bond for used vehicle dealers to $75,000. These safeguards ensure that whether you choose a bank or our finance department, you're operating in a market that prioritizes your security and confidence. Deciding on dealership financing vs bank loan Ohio options becomes much simpler when you know the local rules are working in your favor.
How Dealer-Arranged Financing Works
When you fill out a single application at Tom Whiteside CDJR, our team can reach out to over 10 different lenders instantly. This process allows us to compare offers from local credit unions and national banks simultaneously. Because we handle a high volume of loans, we often have access to rates that a walk-in customer might not see. The Consumer Financial Protection Bureau suggests that shopping around is key to a good deal, and we make that happen without the need for multiple credit-impacting inquiries over several weeks. It's about efficiency. We aim to find a lender that works with your specific credit profile, whether it's excellent or still a work in progress.
Manufacturer Incentives and Captive Lending
The biggest advantage for a dealership is access to captive finance companies like Chrysler Capital. These are the lending arms of the manufacturers themselves. If you're looking at a new RAM 1500 or a Jeep Wrangler, you might find promotional APRs like 0% or 1.9% that traditional banks simply can't match. For many drivers, deciding between dealership financing vs bank loan Ohio options often comes down to these exclusive manufacturer perks. These rates are frequently tied to specific models or loyalty programs, making them a powerful tool for lowering your monthly payment.
We also provide flexible lease vs. buy options directly from the manufacturer, giving you more ways to fit a vehicle into your lifestyle. If you're ready to see what rates you qualify for, you can explore our current vehicle financing options to get started. By leveraging these high-volume relationships, we aim to deliver a professional, polished experience that feels like a conversation with a trusted partner. Our goal is to ensure you drive away with confidence, knowing you secured a competitive package tailored to your needs.
Evaluating Bank and Credit Union Loans
There is a distinct sense of security that comes from working with a financial institution you already trust. Whether you have been with a local credit union for years or prefer a regional bank in Grove City, these established relationships can provide a solid foundation for your purchase. When looking at dealership financing vs bank loan Ohio possibilities, the existing rapport you have with a loan officer can sometimes lead to a more personalized review of your application. It's a comfortable starting point for many drivers in Mount Sterling and London.
Credit unions, in particular, remain highly competitive in 2026. For example, the Credit Union of Ohio has offered rates as low as 5.25% for terms up to 72 months for qualified borrowers. These non-profit organizations often return their earnings to members in the form of lower interest rates. This makes them a vital part of your research. However, remember that these institutions operate with their own sets of rigid criteria that might not always align with every vehicle or buyer profile. While they are great for traditional loans, they may lack the specialized promotional packages found at a dealership.
The Pre-Approval Power Move
Walking into a showroom with a pre-approval letter is one of the smartest moves a buyer can make. It transforms you from a "monthly payment shopper" into a "total cost buyer." This document serves as your baseline. If your bank offers you a specific rate, you now have a target for the dealership to beat. This FTC Consumer Advice suggests that having this benchmark helps you negotiate with confidence. It simplifies the conversation. You don't have to wonder if you're getting a fair deal because you already have a verified offer in your pocket to compare against our network of lenders.
Understanding Bank Loan Restrictions
While banks offer great rates, they also come with specific limitations that can complicate a purchase. Many Ohio banks have strict minimum loan amounts, often starting around $7,500. If you're looking for a budget-friendly used car, you might find that your bank won't even write the loan. They also tend to be wary of older vehicles. A bank might refuse to finance a high-mileage RAM truck or an older Jeep, even if the vehicle is in excellent condition. This is where the dealership financing vs bank loan Ohio debate shifts. We work with specialized lenders who understand the value of used vehicles, providing the flexibility that traditional banks often lack. Additionally, using a bank means you are the middleman. You have to ferry paperwork back and forth, which can delay you from driving home in your new vehicle.
Choosing the Right Path for Your Budget
Finding the right financial path isn't about picking a side immediately. It's a methodical process that ensures your new vehicle fits your life in Mount Sterling or Columbus without causing stress. When you weigh dealership financing vs bank loan Ohio options, the most successful buyers follow a specific sequence. Start by checking your credit score; with the average new car buyer hitting a 751 score in early 2026, knowing where you stand helps you predict your interest rate. Next, secure a baseline quote from your primary bank. This gives you a clear number to bring to the dealership, allowing us to see if our network of lenders can provide a more competitive package.
Comparing the math is where the real work happens. It's vital to look past the monthly payment and examine the long-term impact. Once you have a bank offer and a dealer offer, lay them side by side. We recommend a simple five-step approach:
- Verify your current credit standing and history.
- Get a written pre-approval from your local bank or credit union.
- Calculate the total loan costs for every offer you receive.
- Determine your trade-in value to lower your borrowed amount.
- Review the final dealer contract against your bank's baseline.
Total Cost of Ownership vs. Monthly Payment
It's easy to get caught up in a low monthly payment, but the loan term matters just as much. A 72-month loan might look affordable, but it often results in paying significantly more interest than a 60-month term. The total cost of the loan includes the original principal, all interest charges over the full term, and any applicable documentation fees. Increasing your down payment is a powerful way to secure a lower APR and reduce this total cost. Small changes now lead to big savings later.
The Role of Trade-Ins in Financing
Your current vehicle is a financial asset that can drastically improve your loan terms. A higher trade-in value reduces your loan-to-value ratio, which often makes lenders more comfortable offering their best rates. To get an objective starting point, we recommend using the KBB Instant Cash Offer tool. This provides a transparent value that we can integrate directly into your financing plan. In Ohio, trading in your vehicle also offers a significant tax advantage. You only pay sales tax on the difference between the new car's price and your trade-in's value, keeping more of your hard-earned money in your pocket. If you're ready to see how these numbers work for you, you can apply for pre-approval online and start your journey with a partner you can trust.
Financing Your Next Vehicle at Tom Whiteside CDJR
Choosing between dealership financing vs bank loan Ohio options shouldn't feel like a solo mission. At Tom Whiteside CDJR, we've spent years rooting ourselves in the Mount Sterling community, building a finance department that acts as a bridge between our neighbors and a vast network of competitive lenders. We know that every driver from Columbus to Grove City has a unique story. Whether you're looking for a rugged partner for the job site or a refined SUV for the family, our goal is to ensure you feel like a partner, not just a line on a spreadsheet. We treat every visitor with neighborly hospitality, prioritizing your comfort over a hard sell.
The Tom Whiteside Experience
Our team brings a level of local expertise that big national banks often lack. We understand the specific needs of buyers in Chillicothe and Circleville because we live and work here too. Over the decades, we've cultivated deep, high-volume relationships with a variety of Ohio-based lenders and national institutions. This allows us to advocate for you in ways a single bank branch cannot. If you're searching for RAM trucks for sale Mount Sterling OH, you're benefiting from our specialized knowledge of commercial and heavy-duty vehicle lending. We also offer deep expertise in Jeep financing, ensuring you get a package that accounts for the high resale value of these iconic vehicles.
We pride ourselves on our flexibility and transparency. While the average credit score for new car buyers in 2026 is 751, we know life doesn't always follow a perfect curve. Our finance experts work with a diverse spectrum of credit backgrounds to find a fit that makes sense for your specific profile. We believe in a polished, professional approach that remains highly accessible. This means we'll walk you through every line of your contract, explaining how your trade-in and down payment impact your total loan cost before you sign anything.
Ready to Start Your Adventure?
The journey to your next vehicle can be smooth and efficient. To save time at the dealership, we encourage you to use our secure online tools. By submitting your information ahead of time, you allow our team to begin comparing dealership financing vs bank loan Ohio offers before you even walk through our doors. This methodical approach ensures that when you arrive, we can focus on the fun part: getting you behind the wheel. When you're ready to visit us in Mount Sterling, please remember to bring a few essential items to help us finalize your loan quickly:
- A valid government-issued driver's license.
- Your current proof of auto insurance.
- Your two most recent pay stubs or verified proof of income.
- The title, registration, and any payoff information for your trade-in vehicle.
We're here to make the process as seamless as possible. You can Get pre-approved today at Tom Whiteside CDJR and take the first step toward a deal that feels just right. We look forward to welcoming you into our showroom and helping you drive home with the confidence that only comes from a trusted local partner.
Drive Home with Confidence in Mount Sterling
Whether you're navigating the streets of Columbus or the backroads of Madison County, the choice of dealership financing vs bank loan Ohio depends on your specific financial goals. You now understand that while a bank pre-approval provides a vital baseline, the exclusive Chrysler Capital rates available at a dealership can often lead to a lower total cost for your new Jeep or RAM. By leveraging tools like the KBB Instant Cash Offer, you can simplify your trade-in and reduce your overall loan amount in one streamlined visit.
Our on-site finance experts bring decades of local Ohio experience to the table, ensuring you receive personalized service that treats you like a neighbor. We're here to help you compare every option with transparency and care. When you're ready to take the next step, you can apply for financing at Tom Whiteside CDJR and see how our network of lenders can work for you. We look forward to being your partner in this exciting journey and helping you secure a deal that fits your life perfectly.
Frequently Asked Questions
Does dealership financing hurt my credit score more than a bank loan?
No, choosing dealership financing won't damage your credit any more than a single bank application. Modern scoring models recognize when you are rate shopping for a vehicle. Whether you are exploring dealership financing vs bank loan Ohio options, multiple inquiries made within a short window are typically treated as a single event. Our team handles this process with care, submitting your application to our network of lenders to find you the most competitive terms available.
Can I use a bank loan at any dealership in Ohio?
Most reputable dealerships in Ohio accept outside financing from banks or credit unions. When you bring a pre-approval from your local institution, we view it as a helpful baseline for your budget. Our finance experts then work to see if our network of lenders can beat that offer. This collaborative approach ensures you get the best possible deal while enjoying the convenience of completing your paperwork right here in Mount Sterling.
What is the average auto loan interest rate in Ohio for 2026?
As of August 2026, the national average interest rate for a 60-month new car loan is approximately 6.94%. Your specific rate depends heavily on your credit score. For instance, buyers with excellent credit (800+) often see rates around 7.40% for new vehicles. Those with good credit (670-739) typically find rates near 8.52%. These figures serve as a reliable guide for Madison County drivers as they plan their next purchase.
Is it better to finance through a credit union or a dealer for a used car?
Credit unions like the CU of Ohio offer great rates, sometimes as low as 5.25%, but they often have rigid age and mileage limits for used cars. Dealerships provide a distinct advantage for older vehicles because we work with specialized lenders who understand the lasting value of used trucks and SUVs. If you're looking for flexibility and a lender that works with your specific credit profile, a dealership is often the more versatile choice.
Can I refinance my dealer-arranged loan with my bank later?
Yes, you can generally refinance a dealer-arranged loan with your bank or credit union at any time. Many of our neighbors choose to finance at the dealership initially to take advantage of immediate manufacturer rebates or promotional incentives. Once those benefits are secured, you're free to explore refinancing options to lower your monthly payment further. It's a steady, strategic way to ensure you're getting the absolute most value out of your vehicle purchase.
What documents do I need for auto financing in Mount Sterling?
To ensure a smooth and thorough experience, you should bring a valid driver's license, your current proof of auto insurance, and your two most recent pay stubs. If you have a trade-in, please bring the title and registration as well. Having these items ready allows our on-site experts to finalize your loan quickly. This preparation helps us respect your time and gets you behind the wheel of your new RAM or Jeep much faster.
How does a trade-in affect my car loan approval?
A trade-in acts as a down payment, which significantly improves your standing with lenders. By reducing the total amount you need to borrow, you lower your loan-to-value ratio and become a more attractive candidate for competitive rates. In the dealership financing vs bank loan Ohio market, a solid trade-in can be the key to unlocking lower interest rates. Using our transparent tools ensures you get a fair value that strengthens your overall application.
Are there special financing deals for RAM or Jeep vehicles right now?
We frequently offer exclusive promotional rates through Chrysler Capital that are specifically designed for new RAM and Jeep models. These manufacturer-backed deals can include APRs as low as 0% or 1.9% for qualified buyers, which traditional banks often can't match. These incentives are a fantastic way to lower your total loan cost while driving a rugged, refined vehicle. We encourage you to check our current inventory to see which specific models qualify for these limited-time offers.


